Merchant cash advances and revenue-based financing are often discussed together because both can provide businesses with capital based partly on their sales and cash flow.
That similarity can make the two products appear interchangeable.
They are not necessarily the same.
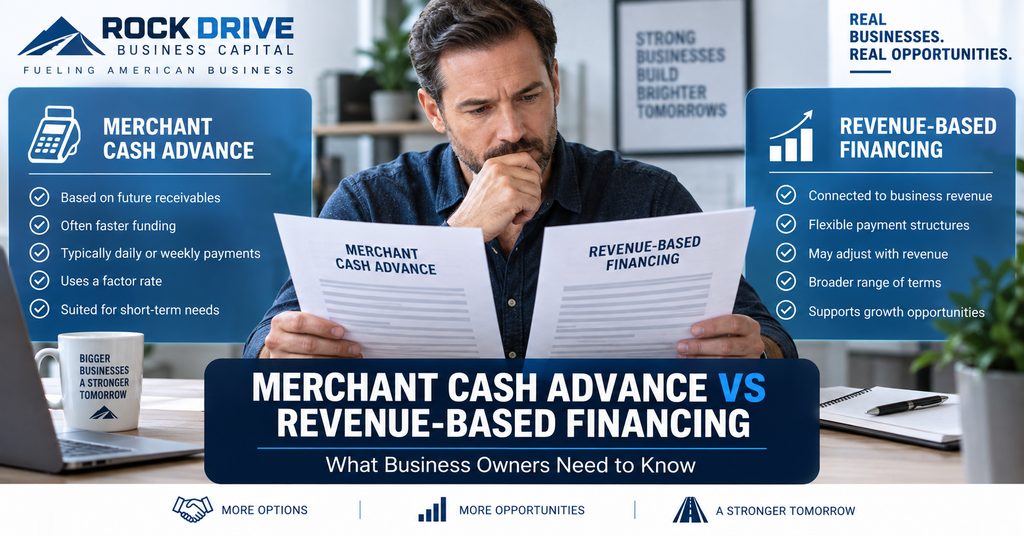
A merchant cash advance (MCA) is commonly structured as the purchase of an agreed amount of a business’s future receivables. Revenue-based financing is a broader term that can cover financing arrangements in which payments or eligibility are connected to business revenue.
The distinction matters because the structure of an agreement can affect payment amounts, payment frequency, total cost, reconciliation rights and what happens when business revenue changes.
For a business owner comparing revenue-based financing vs merchant cash advance, the most important thing is not simply the name attached to the product. It is understanding exactly how the proposed financing works.
Merchant Cash Advance vs Revenue-Based Financing at a Glance
| Feature | Merchant Cash Advance | Revenue-Based Financing |
|---|---|---|
| Basic structure | Commonly an advance in exchange for an agreed amount of future receivables | Broader category of financing connected to business revenue |
| Underwriting | Often focuses heavily on revenue, deposits and cash flow | Commonly considers revenue, cash flow and overall business profile |
| Payments | May involve fixed daily/weekly withdrawals or a percentage of receipts | May involve a percentage of revenue or another payment structure |
| Cost terminology | Often uses a factor rate or purchased amount | Pricing structure varies by agreement |
| Payment flexibility | Depends on agreement and reconciliation provisions | Depends on the specific financing structure |
| Traditional loan? | Commonly structured as a receivables purchase rather than a conventional loan | Depends on the particular product |
Neither option is automatically better. Businesses should compare the actual offers rather than choosing based solely on the product name.
What Is a Merchant Cash Advance?
A merchant cash advance provides a business with an upfront amount in exchange for an agreed amount of future business receivables or revenue.
For example, suppose a business receives:
- Advance amount: $40,000
- Factor rate: 1.30
- Purchased amount: $52,000
$40,000 × 1.30 = $52,000
The business receives $40,000 and agrees to deliver $52,000 according to the payment structure specified in the agreement.
Payments may be collected through automatic bank withdrawals or through a percentage of eligible business receipts.
An MCA is commonly structured differently from a conventional business loan. Business owners should therefore review the actual agreement rather than assuming traditional loan terminology or protections automatically apply.
For a detailed explanation, read our guide to what a merchant cash advance is and how it works.
What Is Revenue-Based Financing?
Revenue-based financing is a broader description of business financing in which revenue plays an important role in determining eligibility, funding amount or payments.
Depending on the provider and agreement, payments might represent:
- A percentage of ongoing revenue
- A fixed daily or weekly amount calculated using historical revenue
- Another agreed payment structure connected to the company’s sales and cash-flow profile
A true percentage-based arrangement may allow the amount paid during a particular period to decrease when revenue decreases and increase when revenue increases.
However, businesses should never assume that payments automatically adjust simply because a product is described as “revenue-based.”
The agreement should clearly explain how payments are calculated and whether an adjustment or reconciliation process is available.
Read our complete guide to revenue-based financing for a deeper explanation of how these structures can work.
What Is the Main Difference Between an MCA and Revenue-Based Financing?
The biggest difference is that revenue-based financing is a broader concept, while a merchant cash advance is a specific type of sales-based transaction commonly structured around the purchase of future receivables.
However, terminology within alternative business financing is not always used consistently.
Two providers could use different names for financing arrangements that have similar economic characteristics. Conversely, two products marketed using similar language could have significantly different payment structures.
That is why business owners should compare the agreement itself.
Pay particular attention to:
- Amount actually received
- Total repayment or purchased amount
- Payment frequency
- Whether payments are fixed or tied to actual revenue
- Estimated duration
- Fees
- Reconciliation or adjustment rights
- Early-payment provisions
- Personal guarantees or security interests
- Default provisions
How Do Payments Differ?
Payment structure is one of the most important areas to investigate.
Percentage-of-Revenue Payments
Suppose an agreement requires 10% of eligible monthly revenue.
If the business generates $80,000:
$80,000 × 10% = $8,000
If revenue later falls to $50,000:
$50,000 × 10% = $5,000
Under a genuine percentage-based structure, payments naturally move with revenue.
Fixed Daily or Weekly Payments
Other arrangements may establish a fixed withdrawal using the business’s historical revenue.
For example:
$1,200 per week
Unless the agreement provides an adjustment mechanism, that $1,200 may continue to be withdrawn even during a slower period.
This distinction can materially affect cash flow.
Business owners should model proposed payments against a weak month—not just their strongest or average month.
What Is Reconciliation?
Reconciliation can be particularly important when comparing merchant cash advances and other revenue-based financing structures.
Some agreements allow a business to request that payments be adjusted to reflect actual receivables or revenue.
Questions to ask include:
- Is reconciliation available?
- Is it automatic or must the business request it?
- What documents are required?
- How frequently can adjustments be requested?
- How quickly are requests reviewed?
- Can payments increase as well as decrease?
- Are there deadlines for requesting an adjustment?
A verbal promise from a salesperson should not replace the written agreement.
Which Option Is Easier to Qualify For?
There is no universal answer.
Providers may consider factors including:
- Average monthly revenue
- Deposit consistency
- Time in business
- Current bank balances
- Existing financing obligations
- Industry
- Credit profile
- Requested funding amount
- Recent negative-balance or overdraft activity
Both merchant cash advances and revenue-based products may place significant weight on current business performance rather than relying exclusively on personal credit.
However, approval standards vary considerably between providers.
If you’re considering an MCA specifically, see our guide to merchant cash advance requirements.
How Much Could a Business Qualify For?
Revenue alone does not determine the funding amount.
Two businesses generating $75,000 per month could receive very different offers.
One may have stable deposits, strong cash reserves and few existing obligations. The other may have frequent overdrafts and several existing daily withdrawals.
A provider may therefore consider both revenue and the amount of cash flow available to support another financing obligation.
Our guide to how much business funding you may qualify for explains these factors in more detail.
Comparing the Cost
An MCA commonly uses a factor rate rather than a conventional interest rate.
If a business receives $75,000 at a factor rate of 1.25:
$75,000 × 1.25 = $93,750
The difference is:
$18,750
That does not automatically tell the business the annualized cost because the time required to deliver the purchased amount matters.
Revenue-based financing can use different pricing structures depending on the provider.
When comparing offers, businesses should therefore look beyond the advertised rate and establish:
How much money will I actually receive?
and:
How much money will I ultimately be required to pay or deliver?
Then consider how quickly those payments are expected to occur.
When Might Revenue-Based Financing Make Sense?
Revenue-based financing may be worth considering when a business:
- Has consistent revenue
- Has a clearly identified use for additional capital
- Can support the proposed payments
- Wants financing evaluated substantially on current business performance
- Has a short- or medium-term opportunity expected to generate sufficient value
Possible uses could include inventory, marketing, expansion, payroll timing or other operating needs, depending on the financing agreement.
The key is that the financing should address a defined business need rather than simply postpone a recurring financial problem.
When Might a Merchant Cash Advance Be Considered?
An MCA may be considered when a business has consistent receivables and needs capital for a specific commercial purpose.
Examples might include:
- Purchasing inventory before a busy period
- Replacing essential equipment
- Covering costs associated with a confirmed project
- Managing a temporary receivables gap
- Funding an opportunity with a measurable expected return
However, the potentially higher cost and frequent payment schedule mean the business should carefully test whether its cash flow can comfortably support the obligation.
What Are the Risks?
Both structures can create problems when the payment obligation is too large relative to the business’s available cash flow.
Frequent Withdrawals
Daily or weekly withdrawals can reduce the cash available for payroll, inventory, rent, taxes and other essential expenses.
High Total Financing Cost
Alternative business financing can cost considerably more than lower-cost financing available to qualified borrowers.
Multiple Financing Positions
Taking additional advances before existing obligations have been completed can create overlapping withdrawals and substantial cash-flow pressure.
Misunderstanding the Agreement
Business owners should not rely solely on labels such as “revenue based,” “flexible” or “working capital.”
The written contract determines the actual obligation.
MCA vs Revenue-Based Financing vs Traditional Business Loan
| Feature | MCA | Revenue-Based Financing | Traditional Business Loan |
|---|---|---|---|
| Primary underwriting focus | Revenue and cash flow plus other factors | Revenue and cash flow plus other factors | Credit, financial performance, cash flow and sometimes collateral |
| Typical payments | Daily/weekly or percentage-based | Varies; may track revenue | Usually scheduled installments |
| Pricing | Often factor-rate/purchased-amount structure | Varies | Commonly interest-based |
| Documentation | Can be relatively streamlined | Varies | May be more extensive |
| Potential cost | Can be comparatively high | Varies | May be lower for qualified borrowers |
7 Questions to Ask Before Choosing
Before accepting either type of financing, ask:
- How much will actually be deposited into my account?
- What is the total amount I will pay or deliver?
- How frequently will payments be taken?
- Will payments automatically change if revenue falls?
- Is reconciliation available?
- Does paying early reduce my total cost?
- Can my business comfortably make these payments during a slow month?
These questions often reveal more than the financing product’s name.
Merchant Cash Advance vs Revenue-Based Financing: Which Is Better?
There is no universal winner.
The better option depends on the business’s:
- Revenue
- Cash-flow consistency
- Existing obligations
- Funding purpose
- Urgency
- Available offers
- Total financing cost
- Ability to manage the payment structure
A lower-cost traditional financing option may be preferable when available and suitable.
If comparing an MCA with revenue-based financing, examine the total repayment, expected duration and payment mechanics of each offer side by side.
A business should choose financing because the economics make sense—not because one product has a more attractive name.
Frequently Asked Questions
Is revenue-based financing the same as a merchant cash advance?
Not necessarily. Revenue-based financing is a broader category of financing connected to business revenue. A merchant cash advance is commonly structured as an advance in exchange for an agreed amount of future receivables.
Is a merchant cash advance a loan?
MCAs are commonly structured as purchases of future receivables rather than conventional loans. The legal treatment of a particular transaction can depend on its terms and jurisdiction.
Does revenue-based financing have fixed payments?
It depends on the agreement. Some arrangements use a percentage of actual revenue, while others may use fixed payments calculated from historical revenue.
Which is cheaper: an MCA or revenue-based financing?
There is no universal answer. Pricing varies by provider, business profile and agreement. Compare the amount received, total repayment, fees and expected payment period.
Can businesses with imperfect credit qualify?
Potentially. Some providers place substantial weight on revenue and cash flow, although credit can still affect eligibility, pricing, amount and terms.
How quickly can funding be received?
Timing depends on the provider, documentation, verification, approval and banking arrangements. Businesses should be cautious of guaranteed funding-time claims.
The Bottom Line
The difference between a merchant cash advance and revenue-based financing is less about marketing terminology and more about the actual financing structure.
A merchant cash advance is commonly based on the purchase of future business receivables. Revenue-based financing is a broader category in which revenue may influence eligibility, funding amounts and payments.
Before choosing either, understand the amount received, total repayment, payment frequency, estimated duration, reconciliation provisions, fees and what happens if sales decline.
Explore Your Business Funding Options
Rock Drive Business Capital helps U.S. business owners explore commercial financing options available through independent financing providers.
Submitting an application does not guarantee approval or funding. Products, amounts, costs, terms and availability vary by provider, applicant and jurisdiction.