Cash flow keeps a trucking company moving. A carrier can have full schedules, reliable customers and profitable loads, yet still struggle to cover fuel, payroll, insurance or an unexpected repair before outstanding invoices are paid. Improving cash flow in a trucking business therefore requires more than increasing sales. It requires tighter control over when cash enters the company, when it leaves and how much each load truly contributes.
The strongest trucking cash-flow solutions combine faster collections, accurate lane pricing, disciplined cost control and forward planning. The following ten strategies can help an owner-operator or fleet manager improve liquidity without losing sight of long-term profitability.
1. Build a Rolling 13-Week Cash-Flow Forecast
A bank balance shows what is available today; it does not show what will be available after next week’s fuel-card settlement, payroll and insurance payment. A rolling 13-week forecast makes those pressures visible before they become urgent.
Start each week with the opening cash balance. Add customer payments expected to clear, then subtract fuel, wages, payroll taxes, equipment payments, insurance, maintenance, permits, financing payments and other essential expenses. Use the actual dates money is expected to enter or leave the account—not invoice dates or accounting entries.
Update the forecast every week and extend it by another week so that it always covers the next 13 weeks. Run a downside version as well. For example, delay a major receivable, increase fuel costs or assume one truck is out of service. The lowest projected balance reveals when the business may need to reduce spending, accelerate collections or arrange additional liquidity.
2. Invoice Immediately and Submit Complete Documents
Every avoidable delay between delivery and invoicing extends the carrier’s cash cycle. Create the invoice as soon as the load is complete and the required documents are available. Confirm that the rate confirmation, bill of lading, proof of delivery, lumper receipt and any accessorial documentation are complete and readable before submission.
Keep a checklist for each customer or broker because documentation requirements can differ. Track rejected invoices and the reason for each rejection. If missing signatures or incorrect reference numbers repeatedly cause delays, correcting that process may release cash faster without adding a new customer or truck.
3. Track the Real Payment Time of Every Customer
Published payment terms do not always reflect actual behavior. Measure the number of days from completed delivery to cleared funds for each customer. Review this figure monthly and separate customers into fast, normal and slow payers.
A customer offering a strong rate may still strain cash flow if it routinely pays late or disputes invoices. When comparing freight opportunities, consider both margin and collection speed. Set reminders before invoices become overdue, follow up consistently and resolve disputes quickly. Concentration also matters: if one slow-paying account represents a large share of receivables, a single delay can affect the entire fleet.
4. Calculate Profit by Load, Lane and Truck
Revenue per mile alone does not reveal whether a load generates enough cash. Calculate the full contribution of each load after fuel, driver compensation, tolls, deadhead miles, detention, maintenance exposure, insurance allocation, dispatch costs and equipment payments.
Review results by customer, lane and vehicle. A busy lane can consume cash if empty return miles, waiting time or frequent repairs are not reflected in the rate. Use recent cost data when quoting work and establish a minimum acceptable margin. When costs change materially, revisit prices, fuel surcharges or the mix of freight accepted.
5. Reduce Empty Miles and Unpaid Waiting Time
Deadhead miles use fuel, driver hours and vehicle capacity without producing freight revenue. Improve dispatch planning by reviewing backhaul opportunities, pickup timing, route sequencing and the performance of regular lanes. A slightly lower-paying load that positions the truck for a profitable return trip may produce better total cash flow than a higher headline rate followed by a long empty journey.
Track detention and layover time as well. Confirm the customer’s accessorial policy before accepting a load, document arrival and departure times, and submit supporting records promptly. Not every delay will be recoverable, but consistent documentation improves the chance of collecting amounts that the contract permits.
6. Control Fuel Spending Without Disrupting Operations
Fuel is both a major expense and an immediate cash demand. Compare fuel-card programs, network coverage, discounts, transaction fees and settlement schedules rather than looking only at the advertised discount. A discount can lose value if it forces drivers off route or comes with costs that are not being tracked.
Monitor miles per gallon by truck and driver, idling time, route choice and unusual purchases. Maintain tires at appropriate pressure and address maintenance issues that reduce efficiency. Forecast fuel by scheduled miles and expected settlement dates so a large card withdrawal does not arrive as a surprise.
7. Create Separate Reserves for Repairs and Large Bills
Money needed for taxes, insurance, registrations or maintenance is not truly surplus cash. Divide large annual, quarterly or irregular bills into weekly amounts and transfer those amounts into designated reserves.
Build the maintenance reserve using the fleet’s real repair history, vehicle age, mileage, warranties and insurance deductibles. A breakdown creates two pressures at once: an immediate repair bill and lost revenue while the truck is unavailable. Setting money aside gradually makes one repair less likely to disrupt payroll or prevent other vehicles from operating.
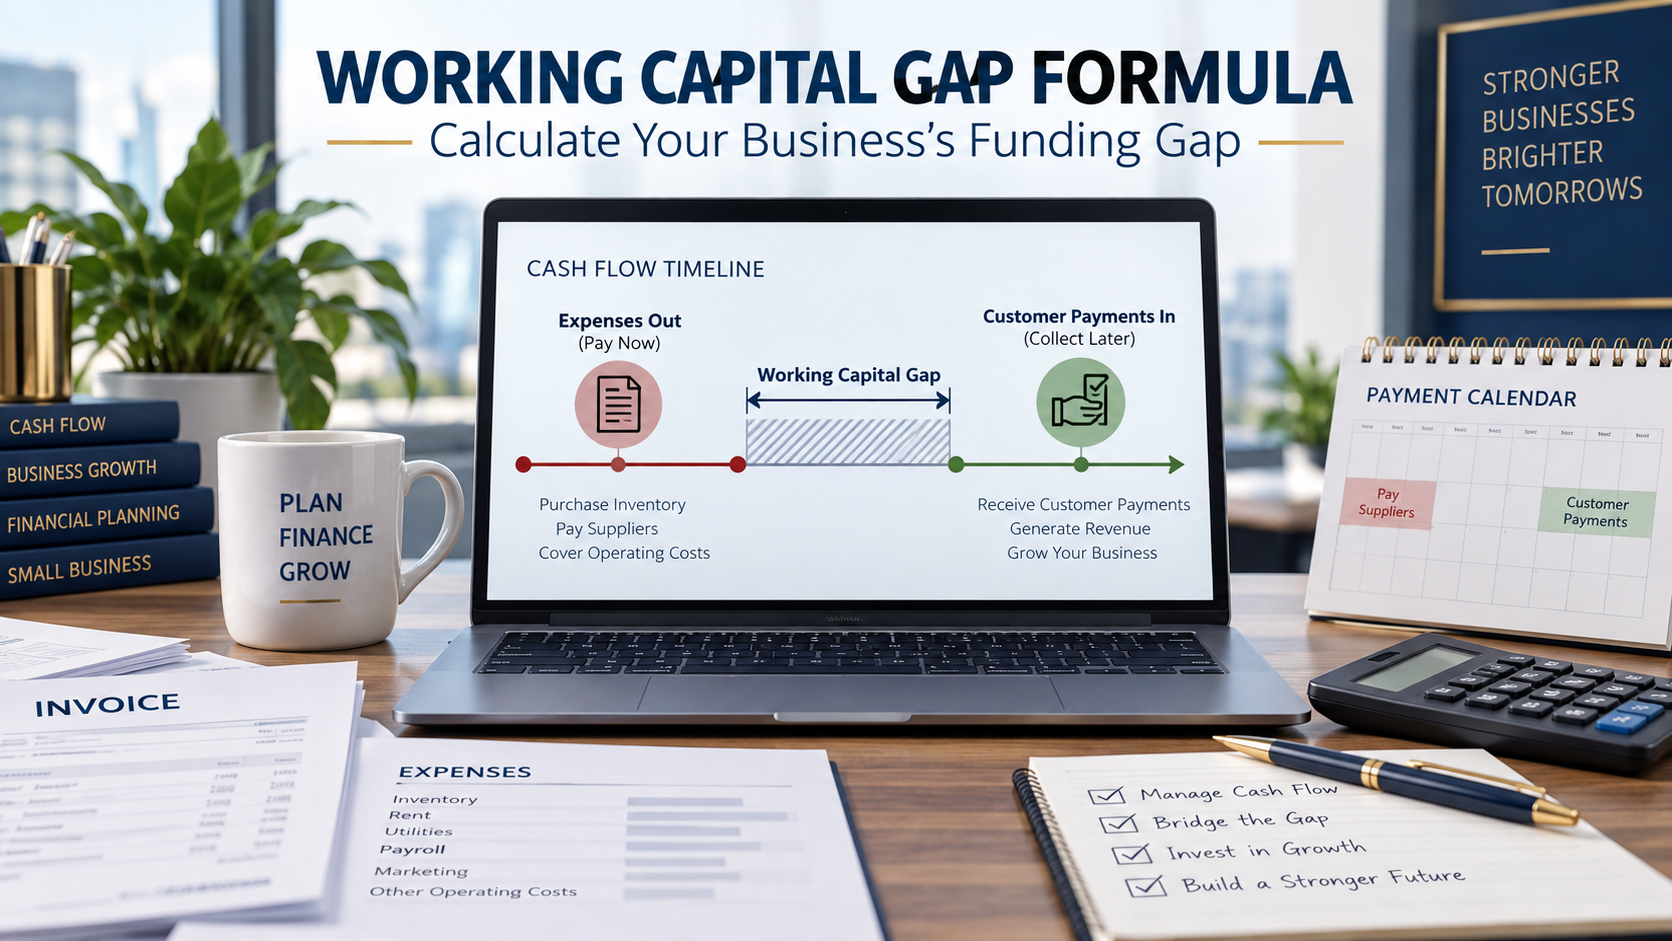
For a structured way to estimate the operating gap and reserve requirement, see how much working capital a trucking company may need.
8. Negotiate Payment Timing on Both Sides
Improving trucking business cash flow is partly about shortening the time to collect and partly about avoiding unnecessarily early payments. Ask reliable customers whether faster terms, electronic payment or an early-payment program are available. Compare any discount or fee with the value of receiving the cash sooner.
On the expense side, review whether insurers, repair shops, tire suppliers and other vendors offer payment schedules that better match the company’s collection cycle. Do not delay obligations beyond agreed terms. The goal is to negotiate transparent terms before a problem occurs, not to create late fees or damage important supplier relationships.
9. Expand at a Pace the Existing Business Can Fund
Growth often absorbs cash before it produces cash. A new truck can require a down payment, registration, insurance, initial maintenance, driver recruitment and weeks of fuel and payroll before the first related invoices are collected.
Before adding a vehicle or route, model the cash needed from acquisition through the expected collection date. Include a slower utilization scenario, delayed receivables and at least one repair. Confirm that the expansion will not drain reserves needed by the existing fleet. Our overview of trucking and transportation business funding explains potential capital uses and financing considerations for carriers.
10. Match Any Financing to a Defined Cash-Flow Need
Financing may help when the forecast identifies a temporary, measurable gap—for example, operating expenses due before dependable receivables are collected. It is not a substitute for correcting consistently unprofitable lanes, uncontrolled overhead or existing payments the business cannot support.
Define the amount needed, how long it is needed and which incoming cash will restore liquidity. Then compare the total cost, payment amount, payment frequency, term, collateral or guarantee requirements and the effect on a slower week. Depending on eligibility and the business need, owners may explore working-capital financing or other commercial financing structures. Product availability and terms vary by provider and applicant.
A Simple Weekly Trucking Cash-Flow Routine
Cash-flow management becomes more effective when it is a repeatable operating routine rather than an emergency response. Set aside time each week to:
- Reconcile the operating bank account and fuel-card activity.
- Update expected customer payment dates invoice by invoice.
- Add known fuel, payroll, repair, insurance and equipment payments to the 13-week forecast.
- Review overdue invoices and assign follow-up actions.
- Check margin and cash performance by truck, lane and customer.
- Transfer the planned amounts into maintenance, tax and insurance reserves.
- Compare the base forecast with a slower-payment or breakdown scenario.
This process turns cash flow from a vague concern into a set of specific decisions. It can also help distinguish a temporary timing problem from a structural shortfall. For more detail on that distinction, read why trucking companies can experience cash-flow problems even when profitable.
Frequently Asked Questions
What is the fastest way to improve cash flow in a trucking business?
The fastest operational improvements often come from invoicing immediately, correcting missing paperwork, following up on overdue invoices and reviewing avoidable fuel or route costs. The result depends on the carrier’s customers, contracts and existing processes.
How can a trucking company prevent cash-flow shortages?
Use a rolling cash-flow forecast, maintain separate reserves, track actual customer payment times and model the cash cost of growth before adding trucks or routes. A downside forecast can show shortages early enough to take action.
Does more revenue always improve trucking cash flow?
No. More loads can increase fuel, wages and maintenance costs before the related invoices are paid. Growth improves cash flow only when loads generate adequate margins and the business has enough liquidity to carry the additional operating cycle.
Should a trucking company use financing to cover a cash-flow gap?
Financing may be considered for a defined temporary need when the projected benefit justifies the cost and payments remain manageable. Owners should review the complete terms and avoid using new financing to conceal ongoing operating losses.
Improve Cash Flow Before the Next Pressure Point
Better cash flow for trucking companies begins with visibility. Forecast the next 13 weeks, collect invoices faster, measure true load economics, reduce avoidable operating costs and protect cash for predictable obligations. These practices give owners more time to respond when a customer pays late, a truck needs repair or a new opportunity appears.
If your established trucking business has a specific capital need, Rock Drive Business Capital can help you explore potential business funding options. Rock Drive is a commercial financing brokerage, not a direct lender. Applications are subject to review and approval by independent financing providers. Products, amounts, costs and terms vary, and submitting an application does not guarantee funding.
Editorial note: This article is for general educational purposes and is not financial, legal or tax advice.