A major truck repair rarely arrives at a convenient time. An engine problem, transmission failure, damaged suspension or emissions-system fault can take a revenue-producing vehicle off the road while creating a bill that must be paid before the truck returns to service. For a small carrier or owner-operator, the challenge is not always profitability. It is often timing: the repair shop needs payment now, while completed loads may not be paid for several weeks.
Truck repair financing can help bridge that timing gap, but the best solution depends on the repair cost, the urgency of the work, available cash reserves and how quickly the business can comfortably repay the funding. Before accepting any financing, calculate the full cost and make sure the expected payment fits the company’s normal cash flow.
Why truck repairs create immediate cash-flow pressure
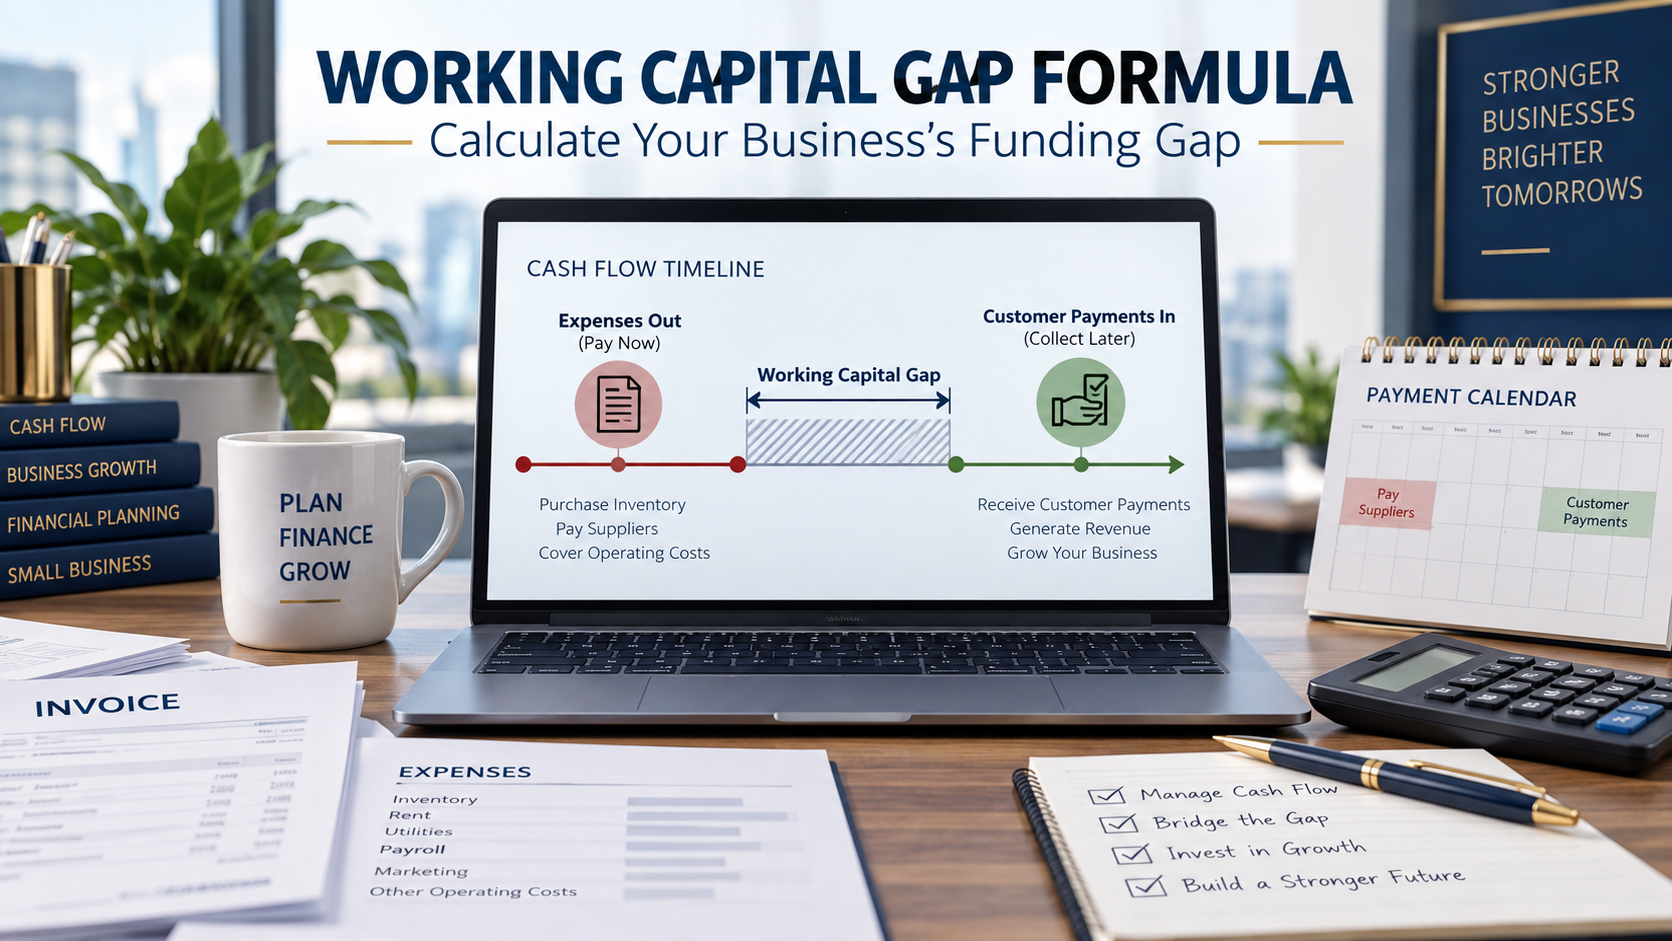
Trucking companies routinely pay operating expenses before collecting customer or broker invoices. Fuel, driver wages, insurance, tolls and maintenance continue to consume cash even when payment terms are net 30 or longer. A breakdown adds two costs at once:
- The repair bill: parts, labor, diagnostics, towing and possible storage charges.
- Lost operating revenue: the truck may not generate income while it is being repaired.
The longer the vehicle remains unavailable, the greater the potential effect on scheduled loads, customer relationships and driver utilization. That is why the least expensive financing option on paper is not always the least expensive business decision. Waiting several weeks for funding could cost more in lost revenue than arranging a faster but moderately more expensive solution.
Carriers facing recurring timing problems should also review these practical strategies for improving cash flow in a trucking business. Better invoicing, expense forecasting and reserve planning can reduce the effect of the next breakdown.
Start by calculating the complete repair requirement
Do not finance only the first estimate without accounting for related costs. Ask the repair facility for a written diagnosis and an itemized estimate. Then calculate the total amount needed using the following framework:
Total funding requirement = repair estimate + towing and related charges + essential operating expenses during downtime − available repair reserves
For example, suppose an engine repair is estimated at $18,000. Towing and diagnostics add $1,500, and the company needs another $5,000 to cover essential expenses while the truck is unavailable. If $7,500 can safely be used from reserves, the potential funding gap is $17,000.
Include a reasonable contingency for repairs that may uncover additional problems, but avoid borrowing substantially more than the business needs. Receiving extra capital can be tempting, yet repayments on unnecessary funding place additional pressure on future cash flow.
Ways to finance commercial truck repairs
1. Use a dedicated maintenance reserve
A repair reserve is normally the simplest and least expensive solution because it does not create a new repayment obligation. Carriers can build the reserve by transferring a fixed amount per truck, per mile or per completed load into a separate account.
However, using every available dollar for one repair may leave the company unable to meet payroll, purchase fuel or respond to another breakdown. Preserve enough liquidity for essential operations. In some cases, combining part of the reserve with a smaller financing facility may be safer than exhausting cash completely.
2. Business line of credit
A business line of credit provides access to an approved credit limit and generally allows the business to draw only what it needs. It can be useful for repairs because the exact final cost may change after the mechanic begins the work. Interest is generally charged on the amount used rather than the entire approved limit, subject to the provider’s terms.
A line of credit is often most useful when arranged before an emergency. Qualification, rates, draw fees and repayment schedules vary, so compare the total cost carefully. Businesses with an available facility may be able to pay the repair shop promptly and repay the balance as customer invoices are collected.
3. Working capital financing
Working capital can be used for short-term operating needs such as repairs, fuel, insurance and payroll. It may suit an established carrier with consistent revenue that needs to return a truck to service quickly. Depending on the product, payments may be daily, weekly or monthly.
The critical question is whether normal operating cash flow can support the payment after the truck returns to the road. Review recent bank activity, existing debt payments and expected receivables before deciding. Rock Drive’s overview of working capital financing explains how this type of business funding may be structured.
4. Equipment financing for major replacements
If the repair requires replacing a major piece of equipment—or if repairing an aging truck no longer makes economic sense—equipment financing may be more appropriate than short-term working capital. The vehicle or equipment commonly serves as collateral, and the cost can be spread over a longer term.
Equipment financing is not necessarily designed for every routine repair. It becomes more relevant when the business is financing a replacement truck, trailer, engine or other substantial asset. Compare the repair cost with the vehicle’s current value, expected remaining life and anticipated future maintenance. Learn more about available equipment financing options before deciding whether to repair or replace.
5. Invoice factoring
Invoice factoring allows a trucking company to sell qualifying unpaid invoices to a factoring company in exchange for faster access to a percentage of their value. It can help when the carrier has completed loads and is waiting for brokers or customers to pay.
Factoring is tied to receivables rather than the repair itself. Fees, reserve requirements, recourse provisions and customer-notification arrangements vary. Compare the cost with the benefit of returning the truck to service sooner, and understand what happens if a customer does not pay.
6. Repair-shop payment plans and warranties
Before taking outside financing, ask whether the repair is covered by a manufacturer, dealer, extended-service or parts warranty. Review maintenance records and previous repair invoices. Even partial warranty coverage can reduce the funding requirement.
Some repair facilities also offer staged payments or third-party financing. Compare their terms with other business funding options rather than accepting the first arrangement offered at the counter.
How to compare truck repair funding offers
Speed matters during a breakdown, but it should not replace proper comparison. Ask each provider for a clear explanation of:
- The total amount the business will receive.
- The total repayment amount and all fees.
- The payment frequency and estimated payment size.
- Whether the rate is expressed as interest, APR or a factor rate.
- Any collateral or personal-guarantee requirements.
- Whether paying early reduces the cost.
- Late-payment, returned-payment and origination fees.
- How quickly funds could realistically become available.
Do not compare offers using the stated rate alone because different products describe pricing differently. Compare the dollar amount received, the total dollars repaid and the time allowed for repayment. A short repayment schedule can strain the business even when the truck is producing revenue again.
Should you repair or replace the truck?
A large repair estimate should trigger a broader commercial decision. Consider:
- The truck’s present market value.
- Total repair spending during the previous 12 to 24 months.
- Expected useful life after the proposed repair.
- Frequency and cost of downtime.
- Fuel efficiency and regulatory requirements.
- Availability and cost of a suitable replacement.
- Whether the replacement payment is sustainable during slower months.
Repairing a dependable truck can be financially sensible when the fault is isolated and the vehicle otherwise has useful life remaining. Repeatedly financing major repairs on an unreliable vehicle can become more expensive than replacement. Use maintenance records and realistic revenue projections rather than making the decision solely on the immediate monthly payment.
Documents that may help the application move faster
Requirements vary by provider, but preparing the following information can reduce delays:
- A written repair estimate or invoice.
- Recent business bank statements.
- Recent revenue information.
- Business identification and ownership details.
- Existing financing balances and payment obligations.
- Truck identification, mileage and maintenance history.
- Accounts-receivable aging or outstanding load invoices, when relevant.
Accurate documentation helps a provider understand the business’s cash flow and the reason for the funding. Never alter an estimate or overstate revenue to obtain a larger approval.
How to reduce the impact of future truck repairs
Financing can solve an immediate problem, but preventive planning is usually less expensive. Build maintenance into the company’s weekly or monthly budget, monitor cost per mile and keep a separate reserve for each vehicle. Review inspection reports promptly and address smaller problems before they become road failures.
It can also help to establish funding relationships before an emergency. Understanding possible trucking and transportation business funding options in advance gives the owner more time to compare terms instead of making a rushed decision while a truck is idle.
Frequently asked questions
Can a business finance an emergency truck repair?
Potentially. Available options may include a business line of credit, working capital financing, invoice factoring or a repair-shop payment plan. Approval and terms depend on factors such as business revenue, time in business, credit profile, existing obligations and the provider’s requirements.
How quickly can truck repair financing be obtained?
Timing varies significantly by product and provider. Some applications may be reviewed quickly when documentation is complete, while bank financing or equipment financing can require more time. No responsible provider should guarantee approval or a specific funding time before reviewing the business.
Can financing cover towing and downtime expenses?
Some working-capital products may be used for multiple legitimate business expenses, potentially including repairs, towing, fuel or payroll. Restricted-purpose financing may only cover specified equipment or repair costs, so confirm permitted uses before accepting an offer.
Is a line of credit better than a term loan for repairs?
A line of credit can offer flexibility for uncertain or recurring repair costs, while a term loan may provide a fixed amount and repayment schedule for a known expense. The better choice depends on availability, total cost, payment structure and the company’s cash-flow pattern.
Explore your truck repair funding options
An unexpected repair does not automatically mean accepting the fastest or largest offer. Determine the complete funding gap, protect essential operating cash and compare the total cost of each option. The objective is to return the vehicle to productive service without creating a repayment burden the business cannot comfortably manage.
If your trucking business needs capital for a repair or another operating expense, explore your business funding options with Rock Drive Business Capital. Submitting an application does not guarantee approval, and all financing is subject to provider underwriting and terms.